
Landing a casino jackpot can be thrilling, but it’s essential to comprehend your tax liabilities. Learning best service ensures you stay compliant with federal tax regulations and steer clear of penalties. All gaming winnings are subject to taxation and must be properly documented on your tax forms.
Comprehending Casino Winnings and Tax Obligations
When you earn winnings at a gaming establishment, the Internal Revenue Service considers these earnings as taxable income, regardless of the amount. Whether you hit a slot machine jackpot, win at a poker table, or receive from sports betting, the IRS mandates reporting of all gambling proceeds. Casinos are obligated to issue Form W-2G for specific wins, typically when amounts exceed specific thresholds such as $1,200 from slot machines or bingo, or $1,500 from keno.
The tax implications of gaming profits extend beyond just the national level, as many states also impose their own taxes on gambling income. You need to keep detailed records of your gambling activities, such as dates, types of games, amounts won or lost, and the names of casinos. These records become crucial during tax time and can help support your claims if the IRS asks for more documentation or conducts an audit of your return.
Understanding your obligations as a gambling winner helps you prevent expensive errors and potential legal issues. The IRS takes unreported income seriously, and failing to declare gambling winnings can lead to penalties, interest charges, and even criminal prosecution in serious situations. Professional tax advisors suggest maintaining all records and supporting documents related to your gambling activities throughout the year to ensure accurate reporting when filing your annual tax return.
IRS Forms and Documentation for Casino Winnings
When you succeed at a gaming establishment, the IRS mandates particular paperwork to track your gambling earnings. Casinos are obligated to disclose certain gambling winnings directly to the IRS with official documentation, and you’ll get copies of these documents for your records. Understanding which documents you’ll get and the timing allows you to prepare for filing season and ensures you have all required paperwork ready when filing your return.
The most common form you’ll encounter is the W-2G, which gaming establishments provide for reportable gambling winnings. However, even if you don’t receive this form, you’re still legally required to report all gambling income. Maintaining thorough personal records during the year offers crucial supporting documentation and helps you accurately calculate your complete gaming earnings and any offsetting losses you may qualify to claim.
Form W-2G: What It Is and Timing of Receipt
Form W-2G is the official IRS document that casinos use to report gambling winnings that meet certain threshold amounts. You’ll receive this form when you win $1,200 or more from slot machines or bingo, $1,500 or more from keno, $5,000 or more from tournament poker, or any winnings subject to federal withholding. The form includes your total winnings, the date of your win, the type of gambling activity, and any federal income tax withheld from your payout.
Casinos typically issue Form W-2G right when your win if it qualifies for reporting, or they’ll mail it to you by January 31st of the following year. The casino will also send a copy directly to the IRS, so the agency already has a record of your winnings. You need to include the information from every W-2G form you receive when filing your taxes, as the IRS will cross-reference your stated earnings against the forms they’ve received from gambling establishments.
What to Do If You Don’t Receive a W-2G
Steps to Take If You Fail to Get a W-2G
Not all gaming payouts trigger the issuance of a W-2G form, but the absence of this document doesn’t eliminate your tax reporting requirement. If your individual wins fall under the minimum thresholds, the casino won’t generate a W-2G, yet you must still report all gaming earnings on your tax return. This includes smaller jackpots, table game payouts, and combined winnings that don’t meet single-transaction reporting requirements but total substantial sums over the year.
If you believe you should have received a W-2G but didn’t, initially reach out to the casino’s accounting or customer service department to verify whether your win met reporting requirements. They can provide duplicate copies if the original copy was misplaced or not received. Keep records of your attempts to obtain unreceived forms, and if needed, report your earnings based on your own records. The IRS requires you to report all income irrespective of whether you received official forms from the payer.
Maintaining Personal Casino Gaming
Keeping detailed personal records of your gambling activity is essential for accurate tax reporting and potential audit protection. Your records should include the date and type of gambling activity, the name and location of the casino, amounts won and lost, and any supporting documentation like receipts, tickets, or statements. Many casinos provide win/loss statements upon request, which summarize your gambling activity for the year and serve as valuable documentation, though these statements alone may not satisfy IRS requirements for deducting losses.
The IRS recommends keeping a gaming journal or record that records each gambling session, including specific details about your winnings and losses. Supplement your written records with corroborating evidence such as gaming tickets, canceled checks, credit card statements, bank withdrawal receipts, and documentation from the gaming establishment. Electronic documentation like screenshots of your online account activity or images of winning tickets can also serve as documentation. These detailed records become particularly important if you intend to claim gaming losses, as the IRS demands documentation for any deductions taken against your gambling winnings.
Step-by-Step Guide to Report Winnings on Your Tax Return
Commence by gathering together all W-2G forms you received from casinos across the tax year. These forms detail your casino winnings and any federal taxes already withheld, functioning as your key resource for accurate reporting.
Next, document your overall gambling winnings on Schedule 1 (Form 1040), specifically on line 8b labeled “Other Income.” Include all winnings, even those without a W-2G form, as the IRS demands complete disclosure of gambling income.
If you itemize deductions on Schedule A, you can deduct losses from gambling up to the total of your winnings. Maintain detailed records such as receipts, tickets, statements, and a gambling diary to support your claimed losses.
Finally, transfer the total from Schedule 1 to your Form 1040 principal return. Review all entries carefully before filing to verify correctness, as differences in your return and casino-reported W-2G forms may initiate an IRS investigation.
Deducting Gambling Losses and Maximizing Your Tax Position
While gambling winnings boost your taxable income, the IRS allows you to reduce these gains by deducting gambling losses up to the amount of your winnings. This deduction can significantly reduce your combined tax obligations, but it requires thorough record maintenance and appropriate submission processes. Learning how to claim these losses is vital for minimizing your tax burden while remaining compliant with IRS requirements.
To report gambling losses, you must detail your deductions on Schedule A rather than taking the standard deduction. This means your total itemized deductions must surpass the standard deduction amount to offer any tax benefit. Keep in mind that you cannot deduct more in losses than you documented in winnings, and losses may not be carried forward to subsequent years if they exceed your this year’s casino income.
How to Deduct Gambling Losses on Schedule A
Gambling losses are reported on Schedule A, Line 16, under “Other Deductions.” You must initially report all your gambling winnings as income on Form 1040, then separately claim your losses as an itemized deduction. This dual-step approach guarantees the IRS can confirm that your reported losses do not surpass your reported winnings. Professional gamblers may have alternative reporting requirements and should consult a tax advisor.
When completing Schedule A, report the total sum of your casino losses for the tax year, making sure it does not exceed your total gambling winnings. You’ll be required to maintain detailed records to substantiate these losses in case of an tax audit. The deduction lowers your AGI only indirectly via itemized deductions, which means it will not impact specific income-dependent calculations or credits that depend on your AGI before itemized deductions are applied.
Documentation Required to Support Loss Deductions
The IRS expects detailed records to validate loss deductions. Qualifying documents include wagering tickets, voided checks, card statements, bank withdrawal records, and statements from gambling establishments. You need to maintain a detailed gambling log that documents the date, kind of gambling, name and location of the venue, gains and losses, and names of companions accompanying you at gambling venues.
Digital records such as casino player’s club statements, online gambling account histories, and electronic payment confirmations are also acceptable forms of documentation. Keep all receipts, tickets, and statements organized by date and gambling session. Many tax professionals recommend maintaining both physical and digital copies of all documentation for at least three years after filing, as the IRS may request verification during an audit of your gambling activities and claimed deductions.
Common Errors and Consequences When Disclosing Casino Winnings
One of the most common errors that taxpayers make is not reporting all gambling winnings, particularly minor sums that don’t initiate Form W-2G reporting. The IRS requires you to report all winnings irrespective of size, and underreporting can result in accuracy-related penalties of 20% of the unpaid tax amount, along with interest that accumulate starting from the original due date of your return.
Another frequent mistake is improperly deducting casino losses as tax deductions without proper records. You must maintain comprehensive documentation including receipts, tickets, statements, and wagering logs to substantiate your losses. Without sufficient records, the IRS may disallow your tax deductions entirely, leading to a increased tax burden and possible audit risk.
Neglecting to file your tax return when you have gambling earnings can result in severe penalties, including failure-to-file penalties of 5% per month up to 25% of outstanding tax debt, legal action in rare situations, and liens on your property. Additionally, casinos report large winnings straight to the IRS, so differences in their records and your return will likely trigger an audit with further examination of your tax history.
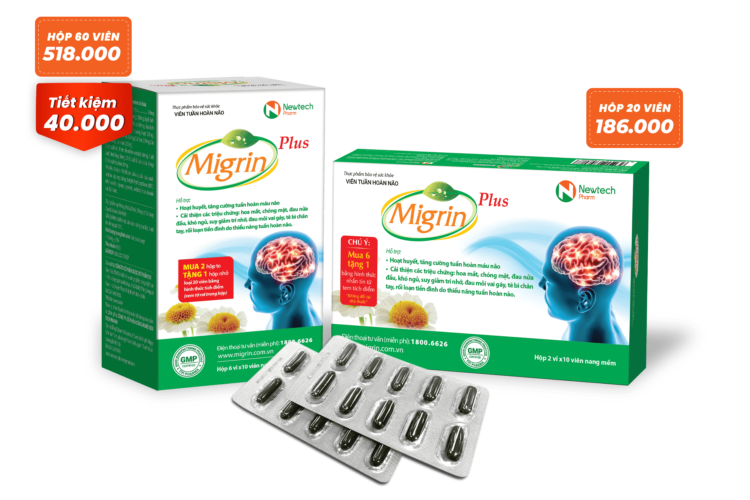


186,000/hộp 20 viên
518.000/hộp 60 viên
Cách dùng
2 viên/ lần x 2 lần/ ngày trong 3 tháng
3 lý do nên lựa chọn Migrin Plus